CPC(TDS) Advisory for Deposit of Tax deducted and Demand for TDS Defaults with respect to Purchase of Immovable Property (26QB Statement-cum-challan)
The Centralized Processing Cell (TDS) provides important tips, for the convenience of Taxpayers, who have executed any transaction for Purchase of Immovable Property exceeding Rs. 50 Lakhs (Rupees Fifty Lakhs). Please take note of the following key details for Payments associated with filing of 26QB Statements-cum-challan and TDS Defaults, if any:
Filing of 26QB Statement-cum-Challan:
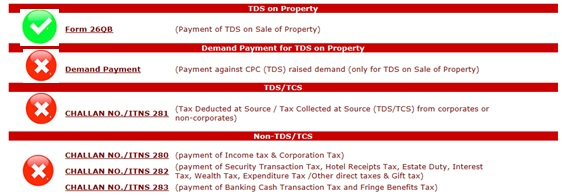
1. 26QB Statement-cum-challan can be filed (along with payment of tax), under “Form 26QB” in “TDS on Sale of Property”on the payment portal of NSDL.
2. The tax to be deposited only through the Statement-cum-Challan mode (Form 26QB). No other challan, viz. Demand Payment, 280/ 281 etc. to be used for the same.
Payment against TDS Defaults:
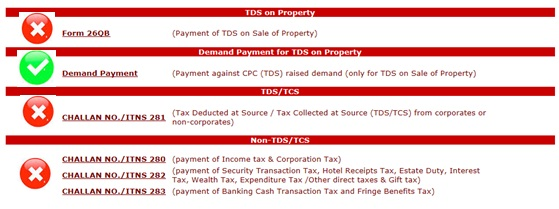
1. On receipt of Default Intimations from CPC(TDS), the Payment against demand raised should be made through the Demand Payment link at NSDL portal, as follows:
2. The payment of Demand for closure of Defaults has to be made only through the above online mode. No other challan, viz. 280/ 281 etc. should be used for payment of demand.
CPC (TDS) is committed to provide best possible services to you.
CPC (TDS) TEAM
Empanelment to act as ICAI exam observers for January 2027 CA Examination. Last date to apply is 20.11.2026 Empanelment of…
No arrest under GST- Major decision taken in 57th Meeting of the GST Council on 8th October 2026 PRESS RELEASE…
A subsequent Apex Court ruling on the substantive issue cannot retrospectively make an act done in compliance of a binding…
Interest payment on mobilisation advance to NHAI not liable for deduction of tax at source u/s 194A - ITAT Interest…
Typographical error in turnover declared in ITR was not as a mistake apparent from the record u/s 154 when AO…
Ground taken by assessee that he was not aware of the order cannot be brushed aside so lightly in absence…